EasyPay U Card: $3 Opening Fee (Historical), Low Barrier — 2026 Archive Check
- Filed
- Virtual Card Reviews
- First run
- 2025-12-20
- Length
- 1002 words

Platform URL:https://easy-pay.site/
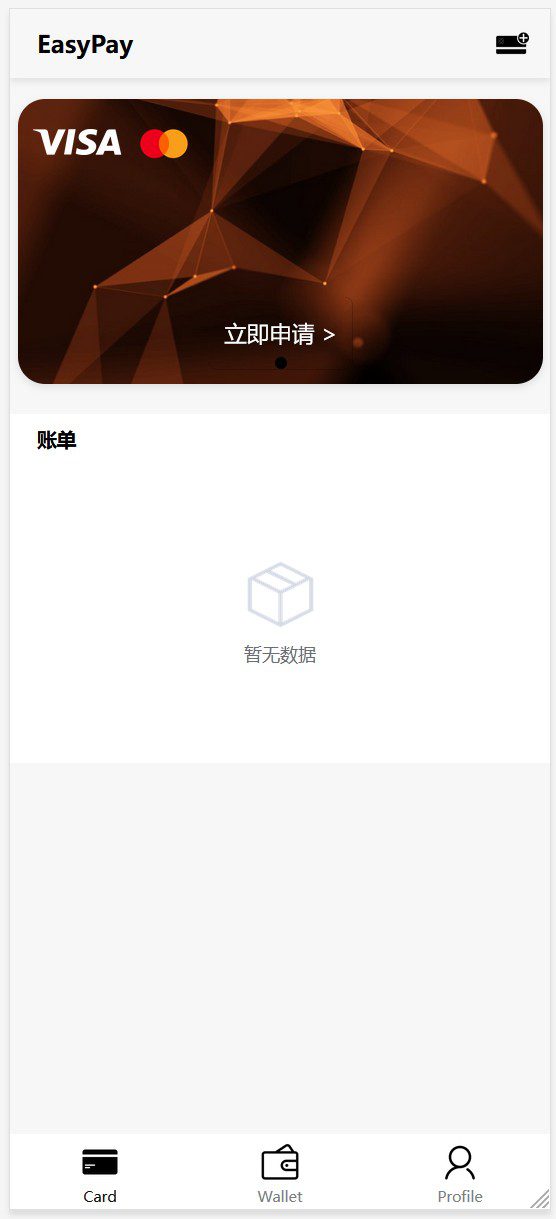
I. Main interface of the platform
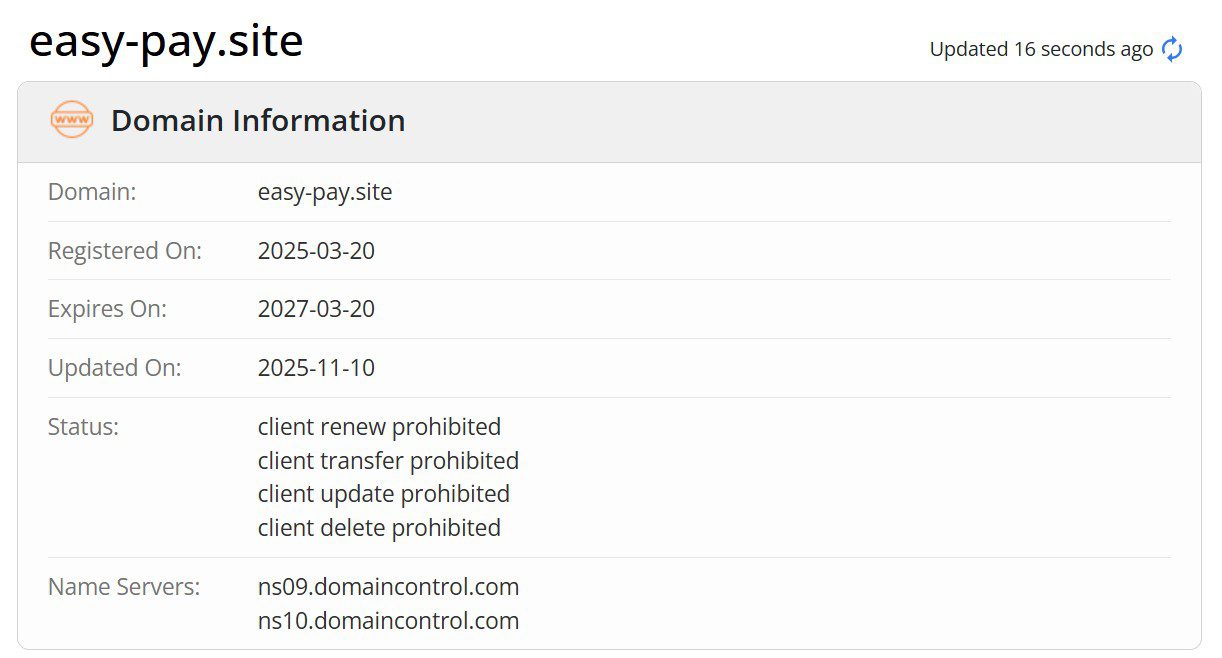
II. When the platform was established
No earlier than March 2025
III. Card opening fees
Only for EasyPay Virtual Credit Cards, there is a card opening fee of 3U per card, a one-time payment that generates card details immediately. Re-checked September 2026 and again on 2026-11-01: the 3U figure reflects earlier hands-on testing; the public site still shows no fixed fee table before login (the landing page remains a redirect shell), and the first deposit must exceed 15 USDT before a card can be opened — confirm the live fee after logging in.
IV. Top-up fee (consolidated)
2% (from earlier hands-on testing; confirm the current rate inside your account).
V. Card BINs and Use Scenarios (official claims)
(i) Virtual credit cards (Visa / Mastercard)
- International e-commerce shopping: available for Amazon (Amazon), eBay, Apple Store, Google Play and other platforms;
- Member subscription services: for ChatGPT, Google Gemini Pro, Adobe, Netflix, Spotify and more;
- Game and entertainment consumption: support Steam, Epic Games, PlayStation, Xbox and other game platform payment;
- Mobile payment binding: can be bound for use in some scenarios of Alipay and WeChat payment.
(ii) Global Transfer Card (function not yet available)
VI. KYC requirements
The public sign-up flow has no KYC (email, code and password only). Note the terms reserve the right to request additional verification when opening/topping up cards or on risk triggers — this is not a promise of permanent anonymity.
VII. Whether you need a cell phone number to register
No.
VIII. Top-up method
Top-ups go through USDT (TRC20) into the account behind a virtual credit card or the global transfer card after registration; funds credit in seconds per the platform. USDT must first be swapped to USD (the platform's "bank balance") before opening a card, the first deposit must exceed 15 USDT, and per platform rules the first three declines caused by insufficient balance in a month are waived — from the fourth, each carries a $0.3 fee, and a monthly decline rate above 20% can get the card deleted automatically by the bank system.
IX. Availability of physical cards
No physical card issuance
X. Standout points
The $3 opening fee sits at the bottom of the U-card range (as of the late-2025 hands-on check; compare against the market when you read this).
KYC-Free U Card – EasyPay: The 3$ activation fee is a highlight: Check these points before reading
Policies regarding virtual credit cards, U-cards, and encrypted payment platforms change rapidly. Card issuance fees, top-up rates, KYC requirements, supported platforms, and risk control rules are all subject to change at short notice. Therefore, when reviewing information about these platforms, don’t just focus on individual fee figures; instead, verify whether the platform is still operating normally, whether it supports your specific payment needs, and whether you can withdraw or transfer funds from your account at any time.
If you plan to use this type of card to pay for ChatGPT, advertising accounts, cloud servers, overseas shopping subscriptions, or cross-border SaaS services, we recommend starting with a small amount to test it out. Once you’ve confirmed it works, gradually increase the amount you load onto the card. Avoid keeping a large balance on a single platform for an extended period right from the start—especially on platforms that lack a clear corporate entity, have slow customer service response times, or have received a lot of negative feedback from the community.
Items to Check Carefully
- KYC Requirements:Confirm whether it is completely KYC-free, has a low KYC threshold, or requires verification only after reaching a certain limit.
- Payment Methods:Check whether USDT, bank cards, Alipay, WeChat Pay, or other payment methods are supported, and calculate the actual loss incurred upon receipt of funds.
- Card Organizations and Card Series:The acceptance rates for Visa, Mastercard, prepaid cards, debit cards, and corporate cards vary significantly across different platforms.
- Consumer Scenarios:Make sure to verify whether the platform supports ad placement, AI subscriptions, international e-commerce, hotel and flight bookings, PayPal, or Apple Pay.
- Risk Control Rules:Familiarize yourself with the rules regarding account freezes, chargebacks, refunds, card cancellations, and balance withdrawals to avoid having your funds held up later.
Recommendations for Use
A safer approach is to have at least two alternative platforms ready: one for regular subscription payments, one for advertising or high-frequency transactions, and one as a temporary backup. This way, even if a platform undergoes temporary maintenance, a payment range is rejected, or fees are raised, it won’t affect ongoing business operations.
If a platform advertises “zero fees,” “permanent KYC exemption,” or “guaranteed approval in any scenario,” you should be even more cautious. Whether a virtual card can successfully process a payment typically depends on the issuing region, MCC, the merchant’s risk control measures, the billing address, the IP environment, and the transaction history—factors that no single platform can guarantee on its own.
Frequently Asked Questions
Are platforms that don't require KYC really better?Not necessarily. While waiving KYC requirements lowers the barrier to opening an account, it may also lead to issues such as low credit limits, strict risk controls, and slow customer service response times. It is suitable for small amounts, temporary needs, and situations requiring a high degree of privacy, but is not suitable for long-term storage of large sums of money.
Why can I use the same virtual card to make payments on some websites but not on others?Different merchants check the card range, billing address, IP address, device environment, and historical chargeback rate. Just because a card is valid doesn’t mean all platforms will accept it.
How can you reduce the likelihood of running into problems?First, check recent reviews, then make a small deposit to test the platform. Be sure to keep records of your transactions and screenshots of your communications with customer service, and avoid leaving a balance sitting in an unfamiliar platform for long periods of time.