 VirtualCardx
PokePay U Card Review: Fees, KYC & Use Cases
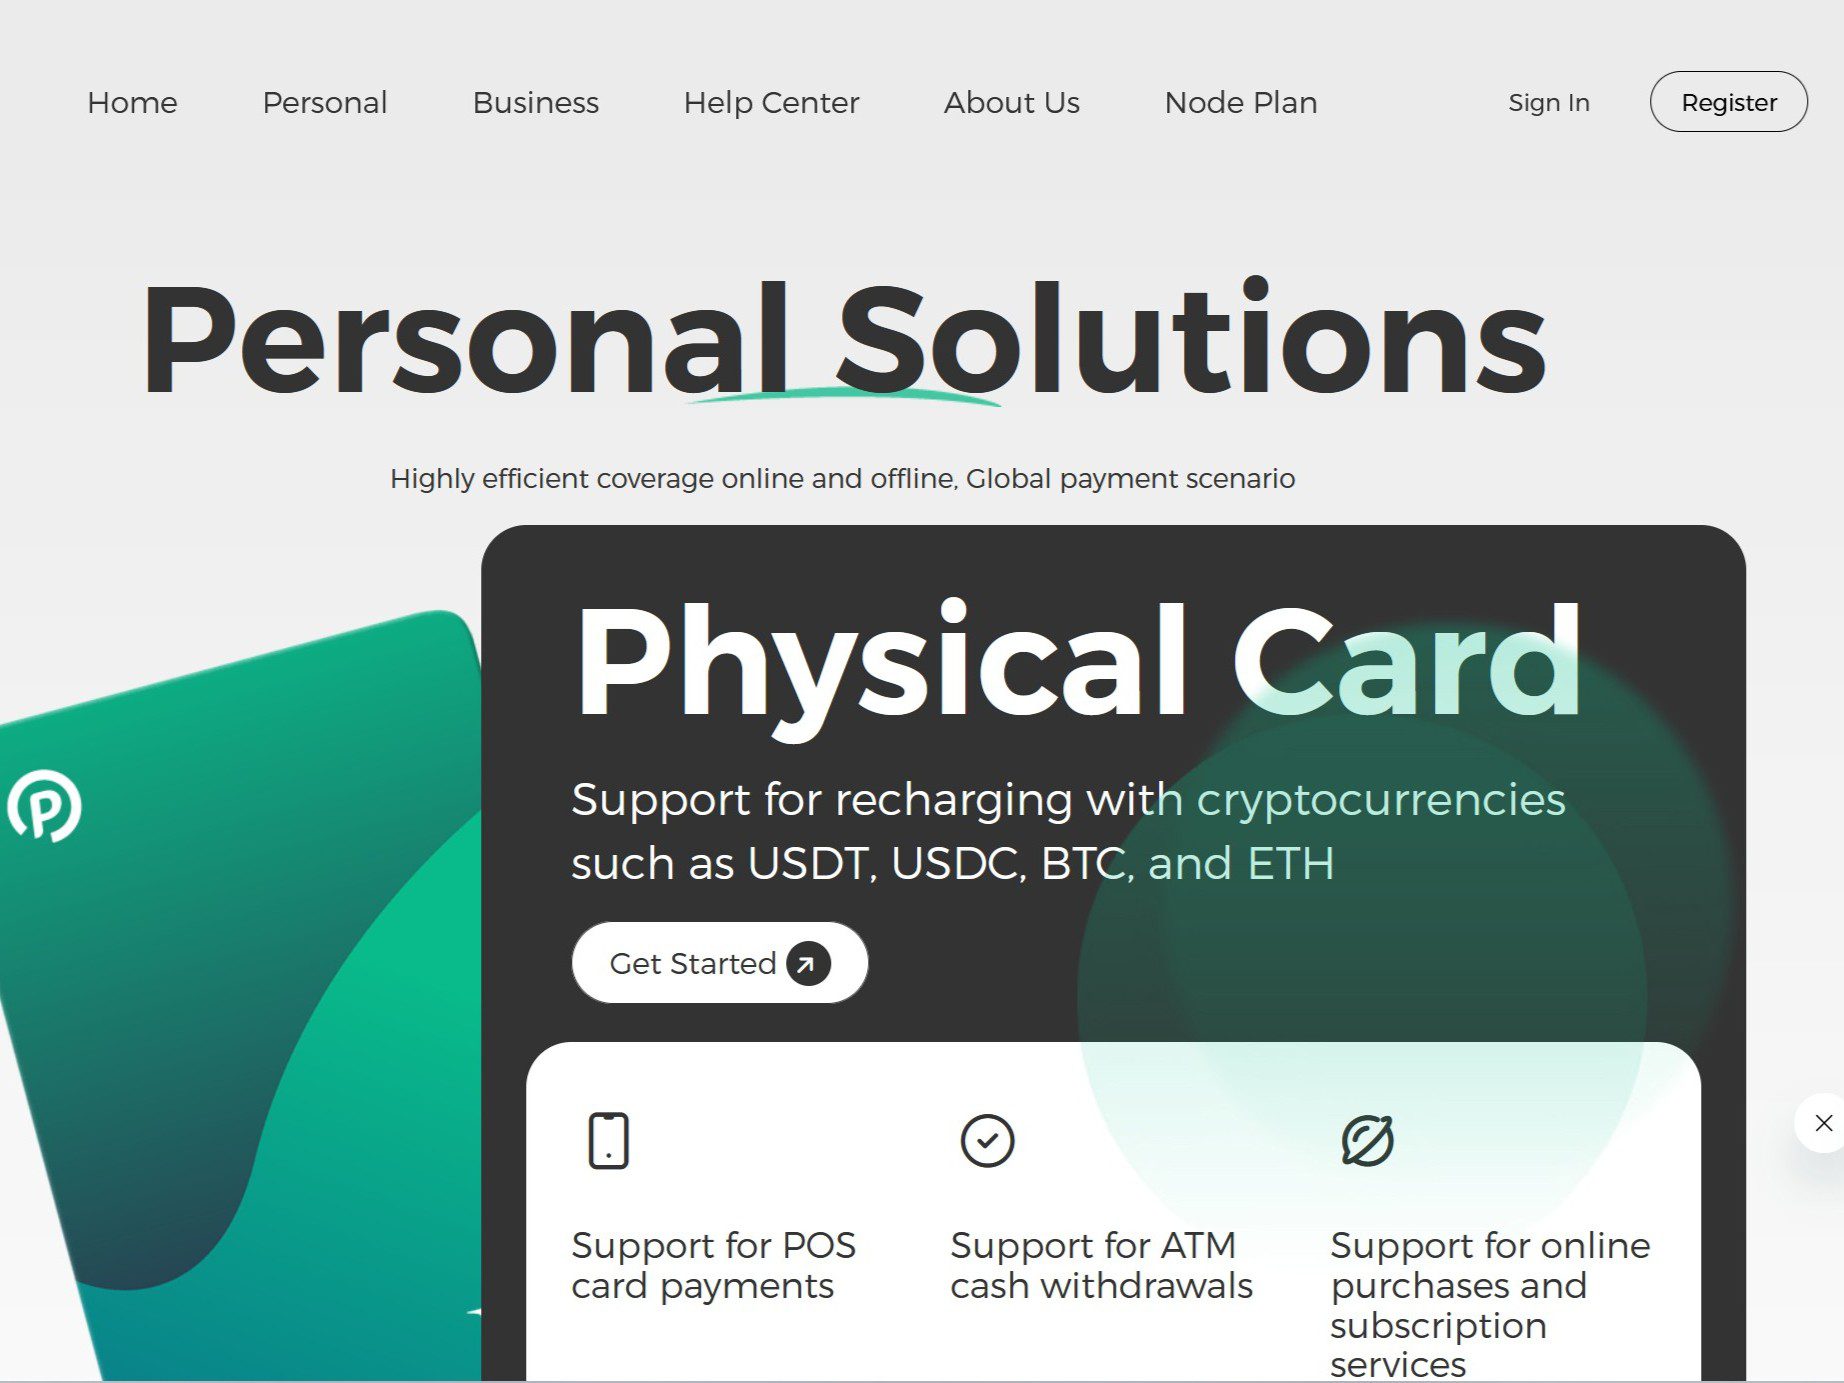
Verification update (2026-09-15): This round checked PokePay's official site (pokepay.cc/hk) directly. The official application flow is register, top up, request a card, complete KYC verification, then activate — KYC is required before a card can be activated. The site also lists a Canada FINTRAC MSB registration (M24040069), an Ontario MSB licence (1551116-0), a Poland VASP registration (RDWW-1657) and a Hong Kong Money Lender's Licence (MLO No. 177/2026). The "currently KYC free" line in the table below contradicts the current official flow and has been annotated; the 5U/88U card fees and 2% top-up rate are historical figures not published on current public pages — check the app for live pricing.
Important: The material below is historical. Except where this update expressly says otherwise, exact claims about pricing, KYC, withdrawals, issuers, licences, BINs, and acceptance were not independently verified in this review and are not current service commitments. Test with a small amount and do not keep a long-term balance.
Registration Portal:https://app.pokepay.cc/pages/invitation/regist?r=462275
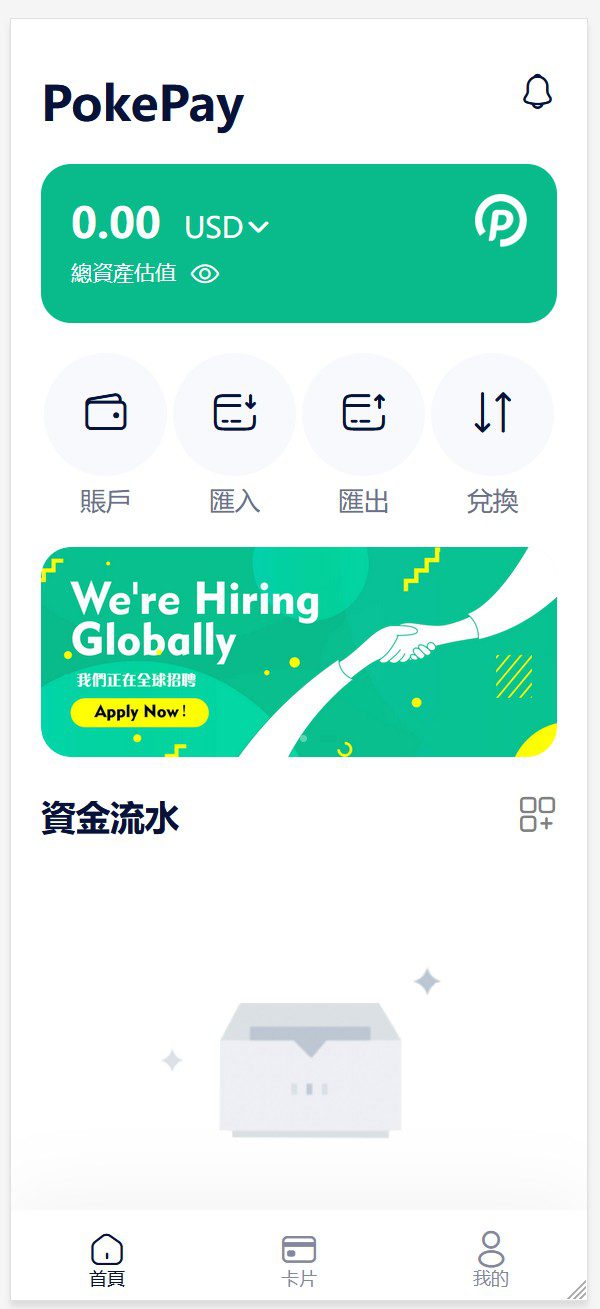
1. Main interface of the platform
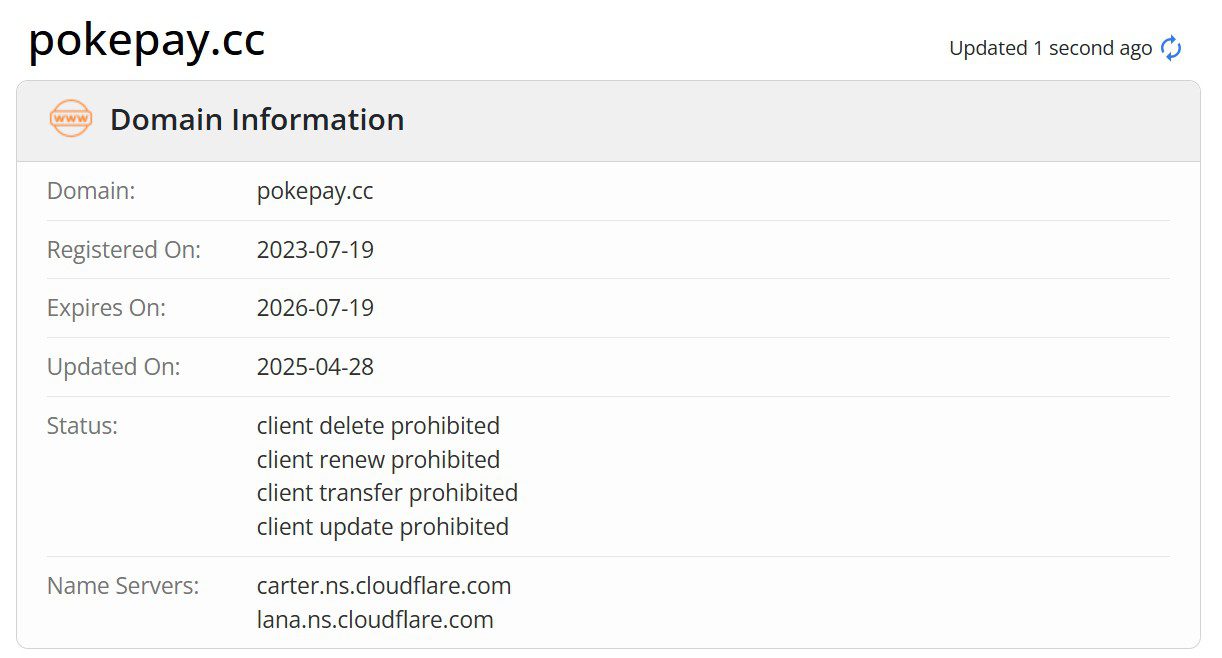
2. When the platform was established
July 2023
3. Card opening fees
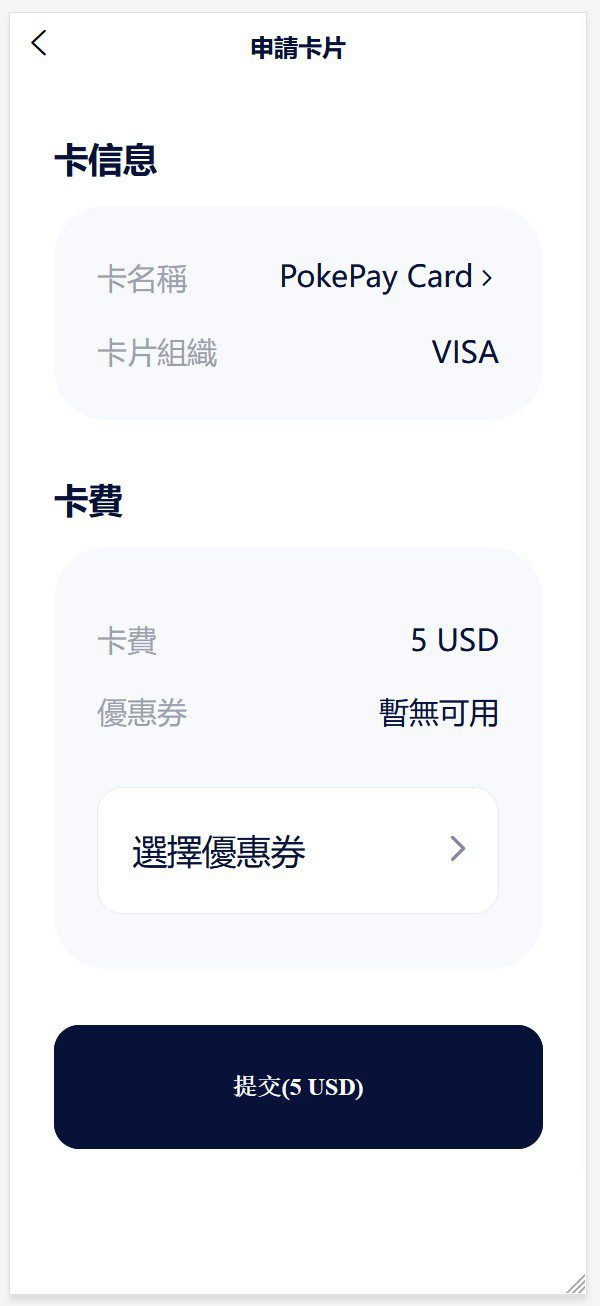
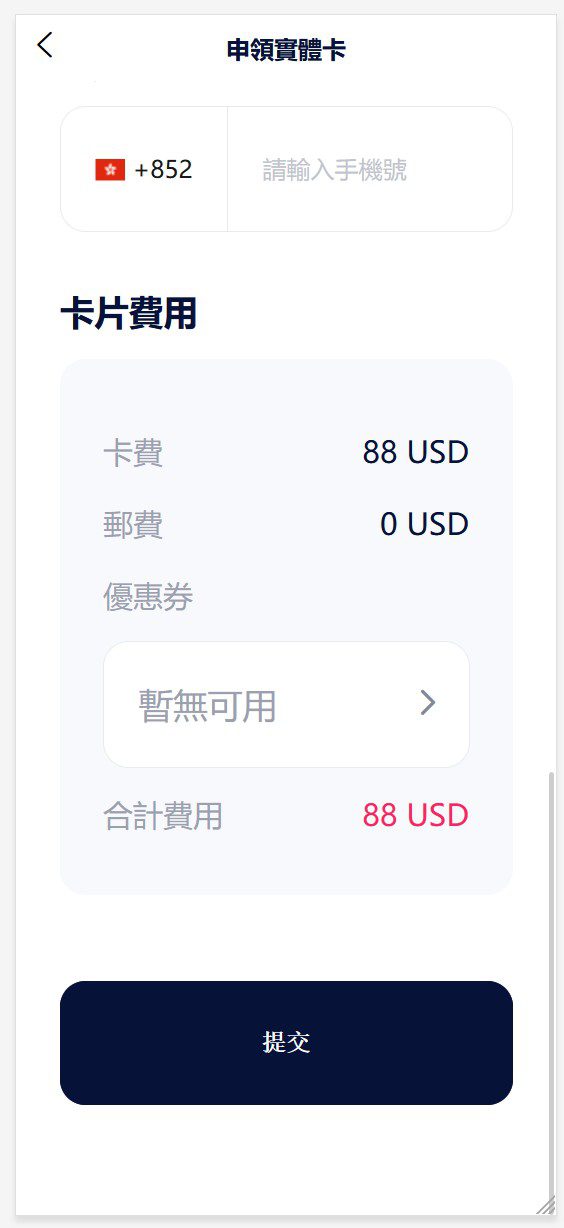
Virtual card 5U, physical card 88U (historical figures; current pricing not shown on public pages — check the app)
4. Recharge rates (consolidated)
2% (historical figure, not confirmed on current public pages)
5. Snap heads (applicable scenarios)
General scenarios are supported
6. KYC requirements
The official application flow now requires completing KYC verification before activating a card (rechecked on the official site, 2026-09-15); an earlier no-KYC period existed historically
7. Whether a cell phone number is required for registration
unnecessary
8. Methods of recharging
9. Availability of physical cards
Yes
10. Featured highlights
Moderate, official app is on google play and apple store
PokePay U Card: Please Check These Points Before Reading
Policies regarding virtual credit cards, U-cards, and encrypted payment platforms change rapidly. Card issuance fees, top-up rates, KYC requirements, supported platforms, and risk control rules are all subject to change at short notice. Therefore, when reviewing information about these platforms, don’t just focus on individual fee figures; instead, verify whether the platform is still operating normally, whether it supports your specific payment needs, and whether you can withdraw or transfer funds from your account at any time.
If you plan to use this type of card to pay for ChatGPT, advertising accounts, cloud servers, overseas shopping subscriptions, or cross-border SaaS services, we recommend starting with a small amount to test it out. Once you’ve confirmed it works, gradually increase the amount you load onto the card. Avoid keeping a large balance on a single platform for an extended period right from the start—especially on platforms that lack a clear corporate entity, have slow customer service response times, or have received a lot of negative feedback from the community.
Items to Check Carefully
- KYC Requirements:Confirm whether it is completely KYC-free, has a low KYC threshold, or requires verification only after reaching a certain limit.
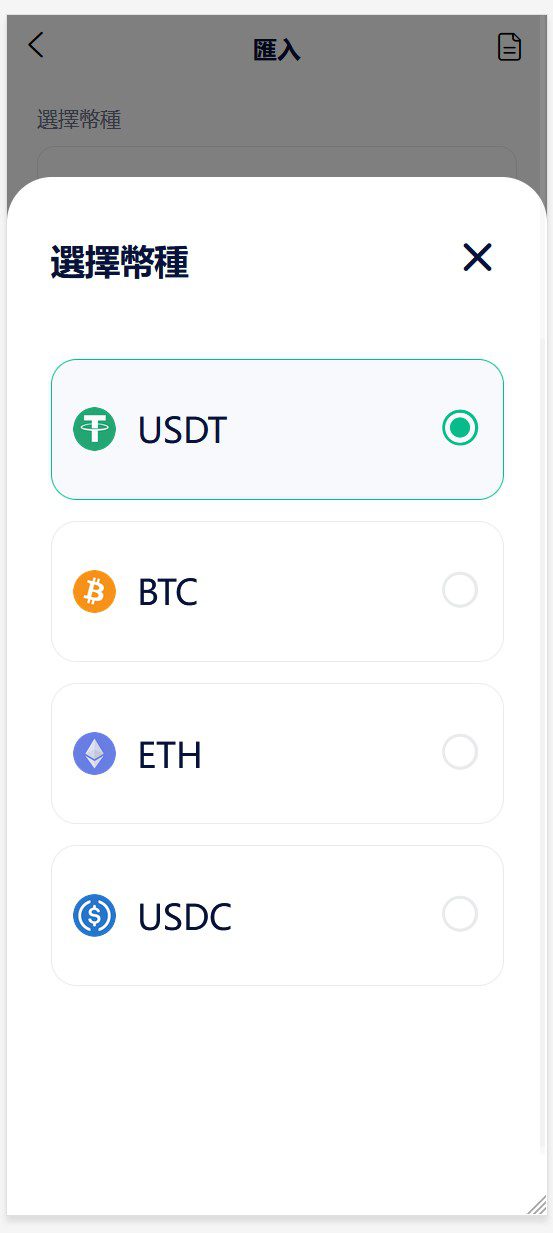
- Payment Methods:Check whether USDT, bank cards, Alipay, WeChat Pay, or other payment methods are supported, and calculate the actual loss incurred upon receipt of funds.
- Card Organizations and Card Series:The acceptance rates for Visa, Mastercard, prepaid cards, debit cards, and corporate cards vary significantly across different platforms.
- Consumer Scenarios:Make sure to verify whether the platform supports ad placement, AI subscriptions, international e-commerce, hotel and flight bookings, PayPal, or Apple Pay.
- Risk Control Rules:Familiarize yourself with the rules regarding account freezes, chargebacks, refunds, card cancellations, and balance withdrawals to avoid having your funds held up later.
Recommendations for Use
A safer approach is to have at least two alternative platforms ready: one for regular subscription payments, one for advertising or high-frequency transactions, and one as a temporary backup. This way, even if a platform undergoes temporary maintenance, a payment range is rejected, or fees are raised, it won’t affect ongoing business operations.
If a platform advertises “zero fees,” “permanent KYC exemption,” or “guaranteed approval in any scenario,” you should be even more cautious. Whether a virtual card can successfully process a payment typically depends on the issuing region, MCC, the merchant’s risk control measures, the billing address, the IP environment, and the transaction history—factors that no single platform can guarantee on its own.
Frequently Asked Questions
Are platforms that don't require KYC really better?Not necessarily. While waiving KYC requirements lowers the barrier to opening an account, it may also lead to issues such as low credit limits, strict risk controls, and slow customer service response times. It is suitable for small amounts, temporary needs, and situations requiring a high degree of privacy, but is not suitable for long-term storage of large sums of money.
Why can I use the same virtual card to make payments on some websites but not on others?Different merchants check the card range, billing address, IP address, device environment, and historical chargeback rate. Just because a card is valid doesn’t mean all platforms will accept it.
How can you reduce the likelihood of running into problems?First, check recent reviews, then make a small deposit to test the platform. Be sure to keep records of your transactions and screenshots of your communications with customer service, and avoid leaving a balance sitting in an unfamiliar platform for long periods of time.